
Possible: Fast Cash & Credit
- Rating
- 4.4
- Downloads
- 1.00M
- Content Rating
- Everyone
Possible: Fast Cash & Credit - Screenshots
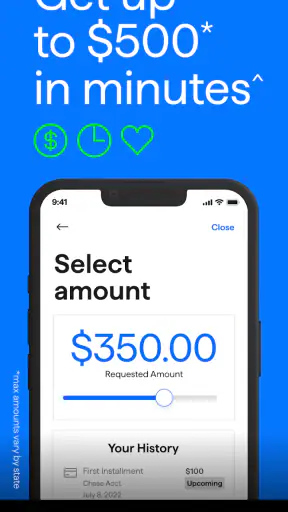
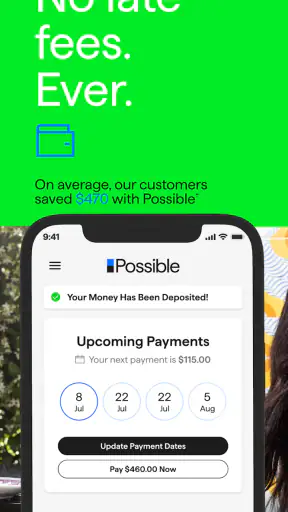
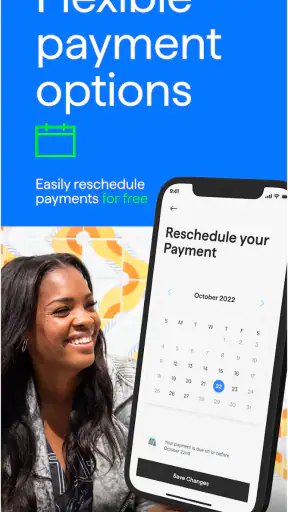
Pros
- Quick application process with minimal paperwork
- Clear repayment information before accepting an offer
- Useful for handling short-term
- unexpected expenses
- Application can be completed from a mobile device
- May connect eligible users with multiple lending options
Cons
- Approval and funding are not guaranteed
- Interest rates and fees may be higher than traditional loans
- Availability and terms vary by location and eligibility
- Late payments can lead to extra charges and credit damage
- May require access to personal and financial information
Possible: Fast Cash & Credit - Description
- App Name
- Possible: Fast Cash & Credit
- Package Name
- com.possible_mobile
- Developer
- Possible Finance - A Public Benefit Corporation
- Category
- Finance
- Last Updated
- Jan 25, 2018
- Version
- 2.5.0
When an unexpected bill lands between paychecks, the hardest part is often not finding an app but understanding exactly what will happen after you tap “apply.” I approached Possible: Fast Cash & Credit with that first-time-user concern in mind. It is a finance app from Possible Finance - A Public Benefit Corporation, built around access to cash and the chance to build credit through flexible payments. My overall impression is that it is most useful as a short-term planning tool, not as a replacement for steady income or a long-term borrowing strategy.
The app is free to install and carries an Everyone age rating, which makes the initial download feel approachable. It has been available since January 25, 2018, and its current version is 2.5.0 for devices running iOS 10 or later. Its public reception is also substantial: the app holds a 4.4 average from around 63 thousand ratings and has passed one million installs. Those figures suggest that many people have tried it, but they should not be mistaken for a promise that every applicant will receive the same result.
What to expect before you begin
The first thing I would tell a friend is to keep the app’s purpose in perspective. Possible is not a budgeting dashboard, a conventional bank account, or a general-purpose credit card. Its focus is narrower: helping eligible users seek cash quickly and manage repayment in a more flexible way while working toward credit-building goals. That focus can be valuable when the need is specific and temporary.
A useful example is a necessary car repair that arrives just before payday. Someone who already knows how the expense will fit into the next few pay cycles may find the app worth exploring. The important question is not simply, “Can I get money today?” It is, “Can I comfortably handle the repayment plan without creating another emergency?” I found that framing much more useful than treating fast access as automatically positive.
The app’s strongest appeal is convenience. Instead of visiting a branch or comparing several traditional financial products, you can begin from a phone. That can be especially helpful for people who prefer a guided digital process or who need to review an option outside normal business hours. The trade-off is that a phone-based experience can make borrowing feel deceptively simple. The taps may be easy, but the financial decision still deserves careful attention.
Possible is also different from a standard credit card. A card can remain available for repeated purchases, while this app is better understood as a focused borrowing and repayment experience. It is not the right tool for building a lifestyle around borrowed money. If your goal is to organize monthly spending, track subscriptions, or create a complete savings plan, a dedicated budgeting app or your existing bank’s tools may serve you better.
Another expectation worth setting is that eligibility and available terms are personal. I would not install it assuming that the same outcome shown to another user will appear on my screen. The sensible approach is to complete the early steps, read every displayed condition, and decide only after seeing the actual repayment details connected to my situation.
The opening screen should lead to a decision, not a rush
For a first-time user, the opening experience is most useful when treated as an information-gathering stage. I would keep my identification and financial details ready, use a stable internet connection, and avoid starting while distracted. Finance applications are not a good place for hurried guesses, especially when a small mistake in personal information can slow the process or require extra review.
I also recommend deciding the purpose of the money before opening the application. “I need cash” is too vague. “I need to cover this specific essential expense and can repay it from these upcoming deposits” is a much safer starting point. That small exercise prevents the app from becoming an invitation to spend simply because an option appears.
Setting up the account without unnecessary friction
The setup process is where I would slow down rather than search for shortcuts. Enter personal information exactly as it appears on your official records, check account details before submitting them, and read each screen instead of accepting prompts automatically. A financial app may need enough information to assess an application and support its credit-related purpose, so accuracy matters more here than it does in a casual social app.
One practical tip is to take a moment before each submission and compare names, numbers, and dates with the original source. Rechecking can feel tedious, but it is easier than trying to diagnose a mismatch later. I would also avoid using a shared device or an unsecured public connection for account setup. The app is free, but free installation does not remove the need to protect sensitive financial information.
The next important habit is to separate the application decision from the repayment decision. If the app presents an available option, do not stop at the amount you can access. Look at the payment timing, the total obligation shown on the screen, and how those payments fit alongside rent, utilities, food, transportation, and existing commitments. The most useful number is the amount you can repay comfortably, not the largest amount the screen allows you to request.
This is also the point where I would answer a common first-time question: is installing the app the same as being approved? No. Installation only gives you access to the application experience. Any offer, eligibility result, or repayment arrangement depends on the information and assessment presented inside the app. I would never make a purchase or promise based on the assumption that approval is guaranteed.
Another question is whether a free download means the service has no financial cost. I would not make that assumption. The app itself is listed as free, but borrowing terms and any amounts connected with an offer must be read inside the application before accepting. The safe workflow is simple: review the complete obligation, compare it with alternatives, and leave the process if the repayment does not make sense for your budget.
Why the credit-building angle needs patience
The credit-building purpose is appealing, but it should not be treated as an instant repair for a damaged credit history. Credit progress generally depends on responsible behavior over time, and the practical value comes from making payments as agreed rather than from merely opening an account. I see this as one of the app’s more important trade-offs: the opportunity may be meaningful, but it requires discipline after the initial approval.
If you choose to use the service, I would place repayment dates beside your normal bills and check your available balance before each one. A small calendar reminder can prevent the common mistake of remembering the loan but forgetting the date. This is a concrete advantage of planning before accepting: the app can support a deliberate routine, but it cannot create money that is not available when a payment is due.
People who already have reliable credit and access to a lower-cost conventional option should compare those choices first. A bank product, credit union option, or existing card may be more suitable depending on the terms and the user’s history. Possible is more compelling for someone whose access to mainstream credit is limited and who values a mobile-first process, provided the repayment plan is genuinely manageable.
Reaching the first meaningful success
For me, the first successful action is not merely completing registration. It is reaching a clear decision with no unanswered questions: either I understand the available repayment arrangement and accept it for a defined need, or I close the app and choose another route. That mindset makes the experience calmer and reduces the chance of borrowing impulsively.
Imagine a user whose refrigerator stops working shortly before payday. They install Possible, complete the requested setup carefully, review the available cash option, and compare the expected payments with their next two paychecks. If the plan leaves enough for essentials, they can proceed with a specific purpose in mind. Afterward, they record each payment date and avoid treating the remaining availability as extra spending money. That is a realistic path to value because it connects the app to one problem rather than turning it into a permanent financial cushion.
My second practical tip is to save a personal note about why the money was requested and when the obligation should be finished. This is not a replacement for the app’s own information; it is a simple way to keep the decision visible when daily life becomes busy. It also helps distinguish a genuine emergency from a repeated pattern that calls for a broader budget review.
A third insight is that flexible payments are helpful only when flexibility supports a plan. If a payment arrangement gives you room to manage timing, that can reduce pressure. If it encourages you to postpone every difficult decision, it can merely move the problem forward. I would use the flexibility to align repayment with known income, not to justify taking more than the original need requires.
After accepting an arrangement, I would return to the app with one purpose: monitoring what I owe and preparing for the next payment. I would not keep checking it out of anxiety, but I would avoid ignoring it. The best result is a predictable routine in which the app becomes a reminder of an obligation rather than a source of repeated emergency borrowing.
Where new users may become confused
The phrase “get cash fast” can create the impression that money is automatic or immediate for everyone. In practice, a user should expect an eligibility process and should read the result shown for their own account. Speed is useful, but it does not override verification, personal circumstances, or the need to understand repayment.
Another point of confusion is the relationship between cash access and credit building. They are connected in the app’s purpose, but they are not identical outcomes. Receiving money solves a short-term liquidity problem; building credit depends on how the account is handled afterward and on the relevant reporting and payment conditions. I would therefore judge the app on two separate questions: does the borrowing option fit this immediate need, and can I follow the repayment arrangement reliably?
Users may also wonder what to do if the available option is smaller than expected or does not fit the expense. My advice is not to fill the gap by stacking several forms of borrowing without a plan. If Possible does not solve the actual problem at a manageable cost, a conversation with the bill provider, a trusted person, a local assistance program, or a traditional financial institution may be safer than combining debts.
Privacy is another reason to be deliberate. I would read the app’s current on-screen explanations and permissions during setup, use a strong device passcode, and avoid sharing login details. I would also keep records of payments and confirmations in a secure place. These habits are particularly important because financial information deserves more care than the average app account.
Finally, the app should not be used by someone who is already missing essential payments and has no realistic way to add another obligation. In that situation, fast cash may provide temporary relief while worsening the underlying shortage. The better next step may be a full review of bills, income timing, and available assistance rather than another borrowing application.
Who will benefit, and who should choose another route?
I think Possible is best suited to a user who needs a defined amount for a short-term gap, wants to handle the process from a phone, and is willing to follow a repayment schedule carefully. It may also appeal to someone interested in credit-building possibilities who understands that progress requires consistent payments rather than a single successful application.
I would be more cautious if the user wants ongoing spending power, rewards, travel benefits, or a broad financial dashboard. Those needs point toward a conventional credit card, bank account, budgeting service, or another specialized product. Possible’s focused design is an advantage when the need matches it, but it becomes a limitation when someone expects an all-in-one money manager.
It is also not my first recommendation for a person who can comfortably wait and save for the expense. Avoiding a borrowing obligation is usually simpler than managing one. Likewise, anyone comparing options should place the displayed terms beside alternatives rather than judging the app only by convenience. A fast application is not automatically the cheapest or most suitable choice.
The developer’s public-benefit identity may be reassuring to some readers, but I would still make decisions based on the actual terms and my own budget. A mission-oriented description does not replace careful reading. The app deserves credit for targeting a real access problem, yet responsible use remains the user’s job.
My next-step advice after installation
If I were guiding a friend, I would suggest a simple sequence. First, install the free app only when you have time to read the screens. Next, prepare accurate personal and financial information, complete setup carefully, and review the result without assuming approval. Then identify the exact expense, study the full repayment arrangement, and accept only if the payments fit after essential bills.
Once the money is used, I would stop treating the app as a source of spare cash. I would mark every payment date, keep enough funds available, and check the account before each scheduled payment. If the arrangement no longer looks manageable, I would seek help early instead of waiting until a missed payment creates a larger problem.
My final view is positive but measured. Possible offers a clear reason to exist, and its combination of fast cash, flexible payments, and credit-building goals can be meaningful for the right user. The experience is most reassuring when you approach it as a carefully evaluated short-term option rather than a quick fix. Use it for a specific need, understand the complete repayment commitment, and let your budget—not the available amount—make the final decision.
FAQ
What is Possible: Fast Cash & Credit, and how does it work?
Possible: Fast Cash & Credit is a financial app designed to let eligible users apply for short-term credit through a mobile device. After creating an account, you provide personal and financial information so the service can assess eligibility. If approved, the loan terms, repayment schedule, fees, and funding options are shown before you decide whether to accept the offer.
Who can use Possible: Fast Cash & Credit, and what are the requirements?
Availability depends on factors such as your location, age, identity, income, banking information, and credit or repayment history. The app may request permission to verify your information and connect to a qualifying bank account. Requirements can change over time, so users should review the current eligibility rules in the app and confirm that the service operates in their state or region.
How much money can I borrow, and how quickly will I receive it?
The amount available is determined individually after the application is reviewed, so there is no guarantee that every user will receive the same offer. Approved funds may be sent to a linked bank account, with delivery time depending on the selected funding method, banking institution, weekends, holidays, and other processing factors. Check the final offer for exact details.
What fees, interest, and repayment terms should I expect?
Before accepting credit, carefully examine the complete disclosure provided by Possible, including the annual percentage rate where applicable, finance charges, subscription or service fees, payment dates, and total repayment amount. Costs and terms may vary according to the product and your application. Missing a scheduled payment could result in additional consequences, so only borrow an amount you can comfortably repay.
Is Possible: Fast Cash & Credit safe to use, and what permissions does it request?
The app may use encryption, identity verification, account connections, and other security measures to process applications and manage payments, but no financial service is completely risk-free. Review its privacy policy, data-sharing practices, and requested permissions before registering. Download only from the official Google Play or Apple App Store, use a strong password, and contact official support if you notice suspicious activity.


